
Health Insurance for Florida Snowbirds: How to Avoid Out-of-State Network Problems
Florida snowbirds may discover that their health plan covers emergencies outside the state but offers limited access to routine doctors, specialists, prescriptions, and follow-up care. Learn how to compare provider networks, out-of-state benefits, Marketplace plans, and private PPO options before choosing coverage for life in two states.
Does My Health Insurance Cover Lee Health, Its Hospitals, and Southwest Florida Specialists?
Does your health insurance cover Lee Health, Cape Coral Hospital, Gulf Coast Medical Center, HealthPark Medical Center, Lee Memorial Hospital, and local specialists? The answer depends on your exact plan and provider network, not just the insurance company name. Learn how to verify hospitals, physicians, specialists, and other providers before enrolling or scheduling care.
Does Health Insurance Have a Maximum Payout?
Most ACA-compliant major medical health insurance plans do not have an annual or lifetime dollar cap on covered essential health benefits. This article explains when benefit maximums can still apply, how those limits differ from out-of-pocket maximums, and what to review in plan documents before choosing coverage.
Marketplace vs. Private Health Insurance in Florida: Which Option May Fit You Better?
Marketplace and private health insurance can provide very different benefits, protections, provider access, and costs. Learn how Florida Marketplace plans, off-Marketplace ACA plans, and medically underwritten private options compare, including subsidies, pre-existing-condition coverage, enrollment rules, networks, and the plan details you should review before choosing coverage.
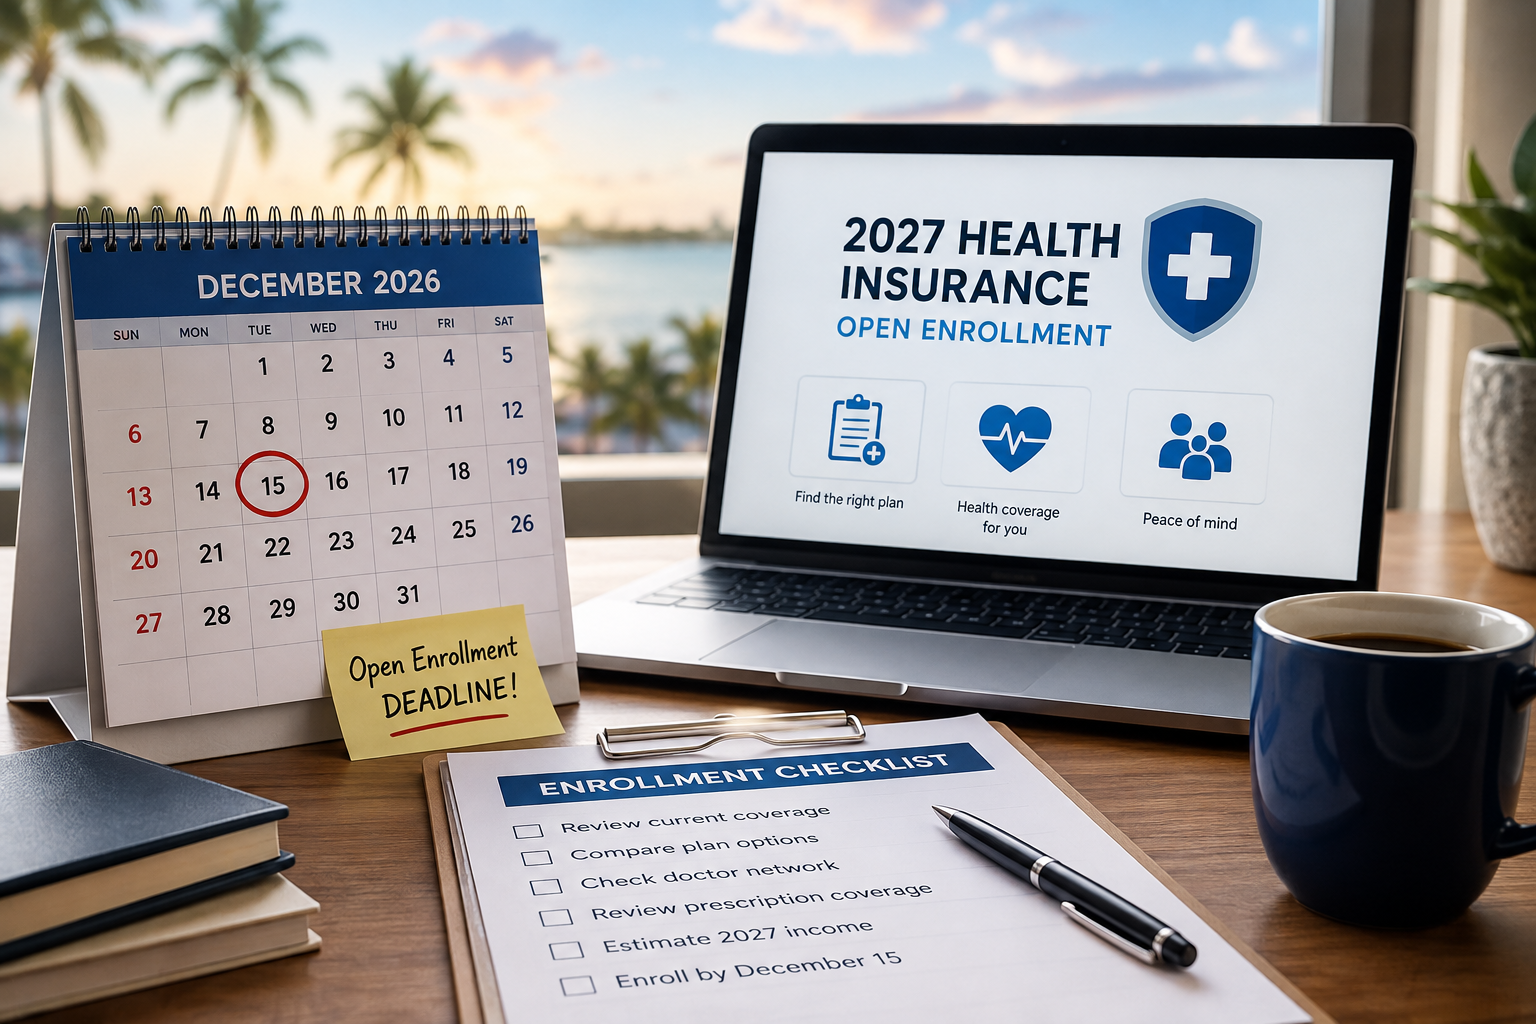
2027 Florida Health Insurance Open Enrollment: The New December 15 Deadline and What Changed
Florida’s 2027 health insurance Open Enrollment period will run from November 1 through December 15, 2026. Learn what changed, why the earlier deadline matters, when coverage begins, and what Florida residents should review before choosing a Marketplace or individual health insurance plan.

What Health Insurance Plans Cover Lee Health, Cape Coral Hospital, or Doctors in Fort Myers?
Before choosing a health insurance plan in Cape Coral or Fort Myers, it is critical to verify whether your doctors, hospitals, prescriptions, and preferred medical facilities are actually covered. Lee Health, Cape Coral Hospital, Gulf Coast Medical Center, and local providers may vary by plan, network, and benefit year, so checking before you enroll can help avoid costly surprises.

How Much Does Health Insurance Cost in Cape Coral or Fort Myers?
Health insurance costs in Cape Coral and Fort Myers can vary widely based on age, household size, income, plan type, provider network, prescriptions, and whether you qualify for ACA subsidies. While many people focus only on the monthly premium, the real cost of coverage includes deductibles, copays, coinsurance, prescription costs, and maximum out-of-pocket exposure. This article explains what Southwest Florida residents should consider when comparing health insurance options and why the lowest monthly payment is not always the lowest overall cost.

Can Self-Employed People and 1099 Contractors Get Health Insurance in Florida?
Self-employed people and 1099 contractors in Florida have several health insurance options, including ACA Marketplace plans, private health insurance, spouse coverage, association options, Medicare, Medicaid, and supplemental coverage. For independent professionals in Cape Coral and Fort Myers, the right plan depends on income, doctors, prescriptions, budget, family needs, and how much financial risk they are comfortable taking.

Can I Get Health Insurance Outside Open Enrollment in Florida?
Wondering if you can get health insurance outside Open Enrollment in Florida? In some cases, the answer is yes. If you recently moved, lost coverage, changed jobs, got married, had a child, or experienced another qualifying life event, you may be eligible for a Special Enrollment Period. For Cape Coral and Fort Myers residents, understanding your timing and options can make the difference between getting covered now or waiting until the next Open Enrollment window.

What Is the Best Health Insurance in Cape Coral or Fort Myers, Florida?
Choosing the best health insurance in Cape Coral or Fort Myers is not just about finding the lowest monthly premium. The right plan should fit your doctors, prescriptions, budget, health needs, and overall risk tolerance. For some people, an ACA Marketplace plan may be the strongest choice. For others, private health insurance, employer coverage, Medicare, Medicaid, or supplemental coverage may offer a better fit. The key is understanding how each option works before you enroll, so you are not surprised later by out-of-network doctors, uncovered prescriptions, high deductibles, or unexpected medical bills.

Do I Qualify for a Health Insurance Subsidy in Florida?
Wondering if you qualify for a health insurance subsidy in Florida? Your eligibility depends on factors like household income, family size, ZIP code, age, and access to other coverage. For Cape Coral and Fort Myers residents, especially self-employed workers, realtors, contractors, and small business owners, accurate income planning can make a major difference in monthly premiums and overall plan affordability.

The Family Deductible Gap: When Having Health Insurance Still Feels Expensive
Many families have health insurance but still struggle with high deductibles, prescription costs, and surprise medical bills. Learn how to identify the “family deductible gap,” compare your true out-of-pocket exposure, and explore private health insurance options that may provide more flexibility, predictability, and financial protection without overpaying for coverage.

Why More Americans Are Rethinking Their Coverage Options
Health insurance should feel like protection, not another financial burden. This article explores why more Americans are rethinking their coverage options as premiums, deductibles, prescriptions, and out-of-pocket costs continue to rise. It also explains why the right plan is not always the cheapest plan, but the one that best balances affordability, access, and real-world protection for your health, family, and finances.

Common Misunderstandings About Indemnity and Fixed Benefit Plans
Fixed indemnity and fixed benefit plans are often misunderstood because they do not work the same way as major medical coverage. Instead of covering a percentage of the bill, these plans typically pay a set dollar amount for specific services based on a benefit schedule. That can be helpful in the right situation, but it is important to understand that the payment may not match the full cost of care. The key is knowing exactly what the plan pays for, what it does not, and how it fits into your overall coverage strategy.

Do Stay-at-Home Parents Need Life Insurance?
A stay-at-home parent may not earn a paycheck, but they often provide thousands of dollars worth of support that keeps a household running. Childcare, transportation, meal prep, scheduling, and day-to-day stability all carry real value. If something unexpected happens, a family may suddenly face major costs just to replace the help they depended on every day. That is why life insurance for a stay-at-home parent is often less about income replacement and more about protecting the family’s ability to function, adjust, and stay financially steady.

Medical Bill vs EOB: What Is the Difference?
A medical bill and an EOB often look similar, but they serve very different purposes. This article breaks down what each one means, why the numbers may not match, and how to review both so you can avoid confusion and make smarter decisions before paying.
Wishing You a Healthy, Hope-Filled New Year
Thank you for trusting us with something as personal as your family’s health and peace of mind. As we step into a new year, remember that small wins—an extra hour of sleep, a short walk, a real conversation—add up. We’re here to offer clarity without pressure and support that fits your life, especially when things change. May your year be full of steady energy, simple joys, and protection that hums quietly in the background—so you can focus on what matters most.
Strong Relationships, Stronger Health: How to Nurture Trust Without the Salesy Stuff
When life gets loud, the quiet power of trust keeps us steady. Decades of research show that close, reliable relationships calm the nervous system, protect the heart and brain, and even add healthy years to life. Trust isn’t built by grand gestures—it grows through small, consistent moments: returning a call, keeping a confidence, showing up on time. Start with one honest check-in today. Your health isn’t just in a plan or a pill bottle—it’s in the people who make you feel safe, seen, and supported.
Your Holiday Mental Health Game Plan
Here’s a calm, science-backed reset for the busiest weeks of the year. If your mood feels like a snow globe in a storm, you’re not broken—your nervous system is doing its job. This guide shows how tiny choices (a 10-minute walk, half-plate of plants, a consistent wind-down, and boundaries you can say out loud) protect sleep, steady emotions, and make room for joy.
2025 Open Enrollment Is Ending: What to Do Now (Without the Pressure)
Open Enrollment for 2025 is closing fast—Dec 15 for a Jan 1 start, or Jan 15 for Feb 1. Take a breath, then choose with clarity: confirm your doctors and meds are covered, compare total yearly costs (not just premiums), and update your 2025 income for accurate savings. If you miss the window, you may qualify for a Special Enrollment Period. Make a calm, confident choice now so you’re protected when life happens.