
SELF-EMPLOYED AND SMALL BUSINESS INSURANCE
Health Coverage for the Way You Work
When work does not include benefits, we help self-employed professionals, independent contractors, and small business owners compare coverage for themselves, families, or employees with guidance from an experienced broker.
Prefer to talk first? Compare my options.
Personally reviewed by Craig Sawyer. No Call Center. No obligation to enroll.
Your Work is Independent. Your Health Coverage Needs a Plan.
You work hard to create opportunities. Your health coverage should support the life you’re building. Whether you are self-employed, an independent contractor, a small business owner, Sawyer Health Solutions helps you understand your options and find a plan that fits your needs, your family, and your budget.
You’ll get straightforward guidance from an experienced broker, not a call center, so you can make confident decisions about your coverage.
Which Situation Sounds Like Yours?
I work for myself.
You’re self-employed, freelance, or independent contractor, and need coverage for you or your family.
I Own a Business and Need Personal Coverage.
You own a business and need health coverage for yourself, with or without a plan for future employees.

I Have Employees.
You’re a small business owner and want to explore coverage options for your team.
Coverage Paths Worth Comparing
ACA Marketplace Coverage
What it is: Health plans through Healthcare.gov
Who may consider it: Individuals and families
Important consideration: Eligibility & subsidies depend on income
Off-marketplace ACA-Compliant Coverage
What it is: ACA compliant plans purchased directly from insurers
Who may consider it: Those who don’t qualify for subsidies
Important consideration: Premiums are the full cost
Private Individual Health Coverage
What it is: Non-ACA compliant plans sold outside the marketplace
Who may consider it: Healthier people wanting more plan options
Important consideration: No premium subsidies. Medically underwritten
Traditional Small Group Health Insurance
What it is: Group health plans for eligible small businesses
Who may consider it: Businesses with 2+ employees (varies by state)
Important consideration: Eligibility & subsidies depend on income
Dental & Vision Coverage
What it is: Standalone plans for dental and vision care
Who may consider it: Individuals, families, & small businesses
Important consideration: Helps cover routine & unexpected care
Accident & Critical Illness Coverage
What it is: Supplemental coverage for unexpected events
Who may consider it: Individuals, families, & small business owners
Important consideration: Helps with out-of-pockets costs.
Life Insurance for Personal or Business Protection
What it is: Financial protection for your loved ones or business
Who may consider it: Anyone who wants to protect what they’ve built
Important consideration: Coverage needs vary by situation.
Short-Term Medical Coverage
What it is: Temporary coverage for limited time periods
Who may consider it: Those in transition (between jobs)
Important consideration: Not ACA compliant, limited benefits.
Not Sure Which Path Fits Your Situation?
Let’s look at your goals, your budget, and your options together.
No call center. No obligation to enroll. Just honest answers from a real broker.

Health Insurance Cost Comparison Calculator
Get a quick estimate of your monthly health insurance costs in just a few steps.
When Income Changes, Your Coverage May Need to Change, too.
If your income fluctuates, you may qualify for different coverage options or savings. We’ll help you understand when it makes sense to revisit your plan so you can stay covered and avoid surprises.
Life changes. Your coverage should keep up.
A well-designed benefits strategy can help you attract and retain great people while keeping your business healthy. We’ll help you compare options and find a solution that fits your team and your budget.
Exploring Benefits for a Small Team?
Questions to Resolve First
How many employees will you be covering?
Do you want to offer one plan or multiple options?
What is your budget?
Are you open to voluntary benefits?
Talk with Craig about employee benefit options >

Award Winning Guidance You Can Trust
2025 Cape Coral Community Votes Gold Winner
Independent health and life insurance guidance for individuals, self-employed professionals, and small business owners.
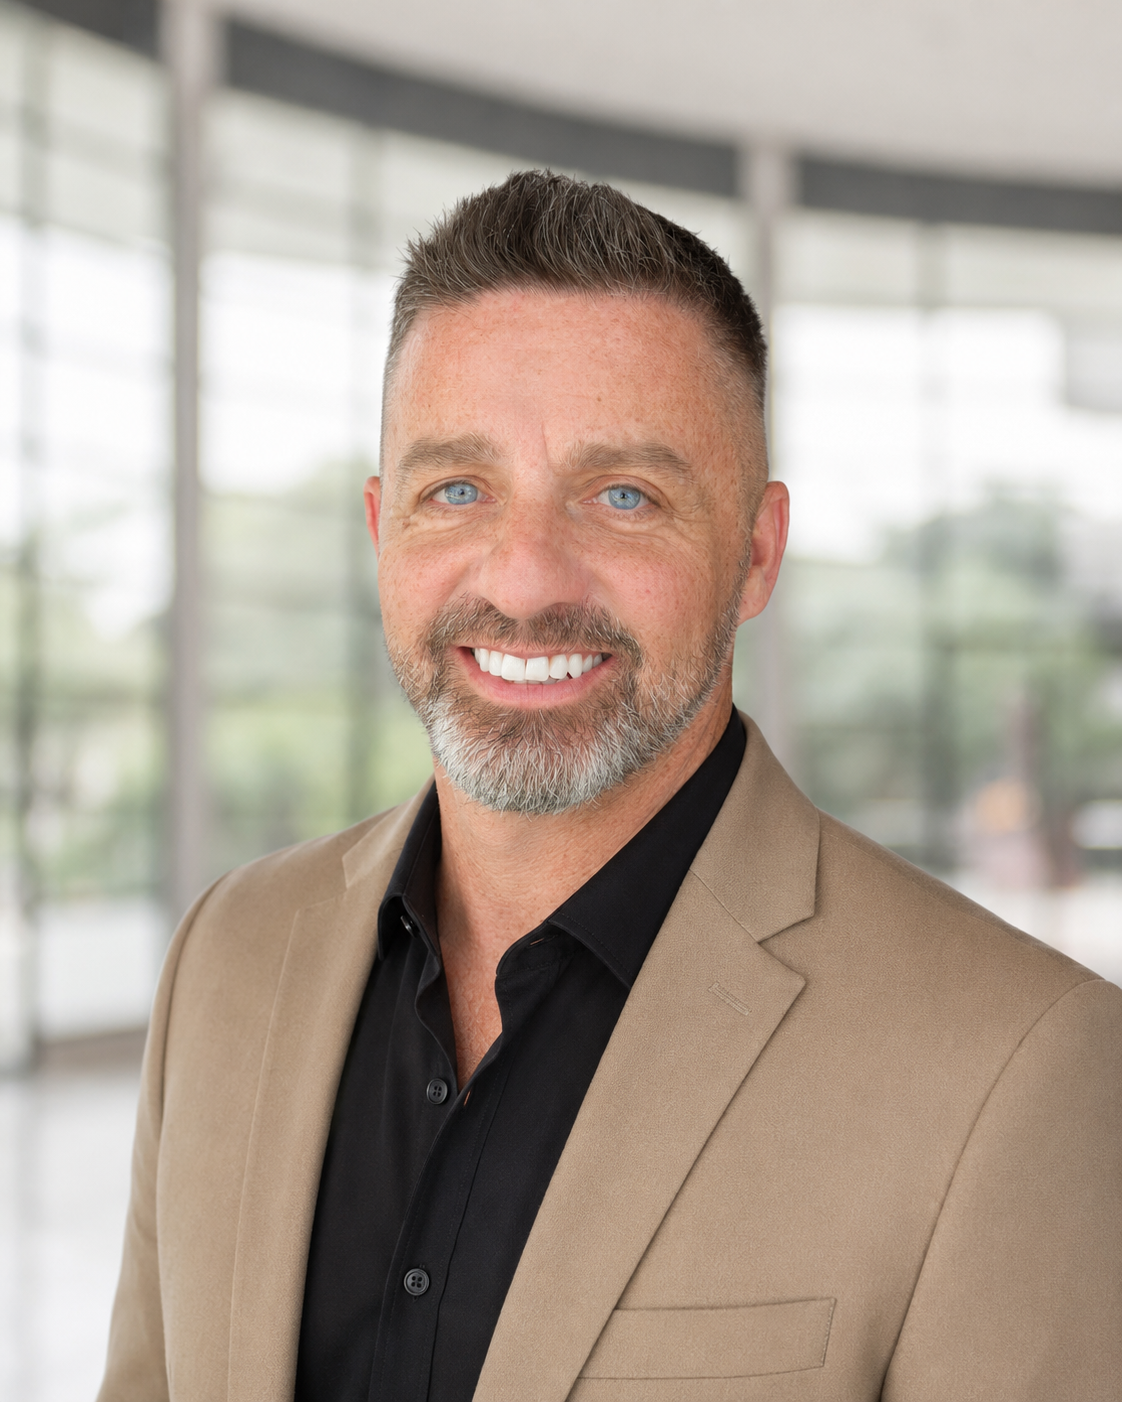
Craig Sawyer
Independent Health & Life Insurance Broker
A Simple, Personal Process
Share a few details about your situation and what matters most.

1. Tell Us What You Need
2. We Review Your Options

We compare available options and explain them clearly.
3. Compare Without Pressure

Get clear recommendations and can decide at your own pace.
Common Questions
-
Small business owners and 1099 contractors can explore individual or family coverage, including medically underwritten private plans and ACA coverage.
Sawyer Health Solutions compares private options from multiple carriers based on your budget, health history, doctors, and prescriptions. These options may be worth considering if you receive little or no Marketplace financial assistance. We help you understand the benefits, limitations, and potential expenses before applying.
-
Private options may be worth comparing if you are generally healthy, receive little Marketplace assistance, or want different networks and benefit structures.
We review premiums, underwriting, exclusions, waiting periods, and coverage limits. Some private products provide limited benefits and are not substitutes for comprehensive major medical insurance. ACA plans are also private insurance and may be more suitable for people with pre-existing conditions, ongoing treatment, or meaningful financial assistance.
-
Yes. You can explore private coverage for yourself, your spouse, and your children, subject to eligibility and availability.
We review everyone’s doctors, prescriptions, and healthcare needs. With medically underwritten plans, family members may receive different premiums, approval decisions, exclusions, or waiting periods. Approval does not guarantee coverage for an existing condition. Sometimes combining different coverage options across your household makes more sense than placing everyone on the same policy.
-
Costs depend on your age, location, family size, and selected benefits. Health history can also affect medically underwritten private coverage.
If you pay full price for your current plan, comparing private options may be worthwhile. We review monthly premiums alongside benefits, exclusions, and potential medical expenses. A lower premium does not always mean lower overall costs. Marketplace assistance should also be checked using your projected annual household income, including net self-employment income.
-
Check the exact policy, network, and prescription benefits before enrolling. Some private plans offer PPO network access, but participation must be verified with the insurer and provider.
We help you review your preferred doctors, Lee Health facilities, medications, and policy limitations. Prescription discounts are different from insurance benefits. With fixed-benefit coverage, the policy may pay less than your medical bill, even when you use a participating provider. A maximum benefit limits the insurer’s payment, not your remaining expenses.
-
Generally, a Florida small group plan requires a qualifying employee beyond the owner and family members, plus applicable carrier requirements.
You do not need employees to explore private individual or family coverage. Solo business owners, freelancers, and 1099 contractors can compare medically underwritten options based on their own needs and eligibility. If you have employees, Craig can discuss your business structure and goals to help identify the coverage paths worth exploring.
-
Yes. Introducing employees to an insurance broker can help them explore individual coverage without establishing a traditional group plan.
Eligible workers can compare medically underwritten private options, while ACA coverage may better fit others. Dental, vision, life, and supplemental options may also be available, although limited benefits do not replace comprehensive medical insurance.
Introducing a broker is different from sponsoring a health plan. Employer contributions, endorsement, or administrative involvement require additional review before setting up an arrangement.
-
Yes, but contributions need to follow applicable requirements. Informally reimbursing premiums can create compliance problems.
Depending on eligibility, employers may consider a QSEHRA or individual coverage HRA, also described by HealthCare.gov as a CHOICE Arrangement. These have rules for qualifying coverage, documentation, notices, and Marketplace assistance. Short-term or limited-benefit coverage alone does not satisfy an individual coverage HRA’s coverage requirement.
Ask Craig about available insurance guidance, and have a qualified benefits administrator and tax adviser review the contribution arrangement.
-
Some medically underwritten private and supplemental products accept applications year-round, subject to carrier rules, eligibility, and approval.
Florida’s 2027 ACA Marketplace Open Enrollment runs November 1, 2026, through January 15, 2027. Enroll by December 15 for January 1 coverage, or by January 15 for February 1 coverage, with the required first premium payment.
Individual ACA plans outside the Marketplace generally require Open Enrollment or a Special Enrollment Period. Employer group plans follow separate rules. Confirm your new coverage before canceling an existing policy.
-
Craig reviews your request and follows up to discuss your budget, doctors, prescriptions, and coverage needs. You can explore available private options and ask questions about benefits, underwriting, exclusions, and potential expenses.
Submitting a request does not enroll you in coverage or guarantee approval or pricing. Employers can schedule a call to discuss coverage paths for their team.
There is no obligation to enroll. Request a personalized quote or call (239) 677-9877 to get started.